

There is a visceral, quiet terror in checking your bank app before you even get out of bed in the morning.
Recently, a short story circulated on X that perfectly encapsulated the financial fragility hidden behind closed doors in high-income neighborhoods. It read like a modern cautionary tale:
A guy making $260k in tech. Nice house, $4,700/month mortgage, two cars, vacations every few months. Got laid off 6 months ago. Still nothing. Down to $22k and burning $5,500 a month. Wife at home, one kid. He told me he checks his bank app before he even gets out of bed now.
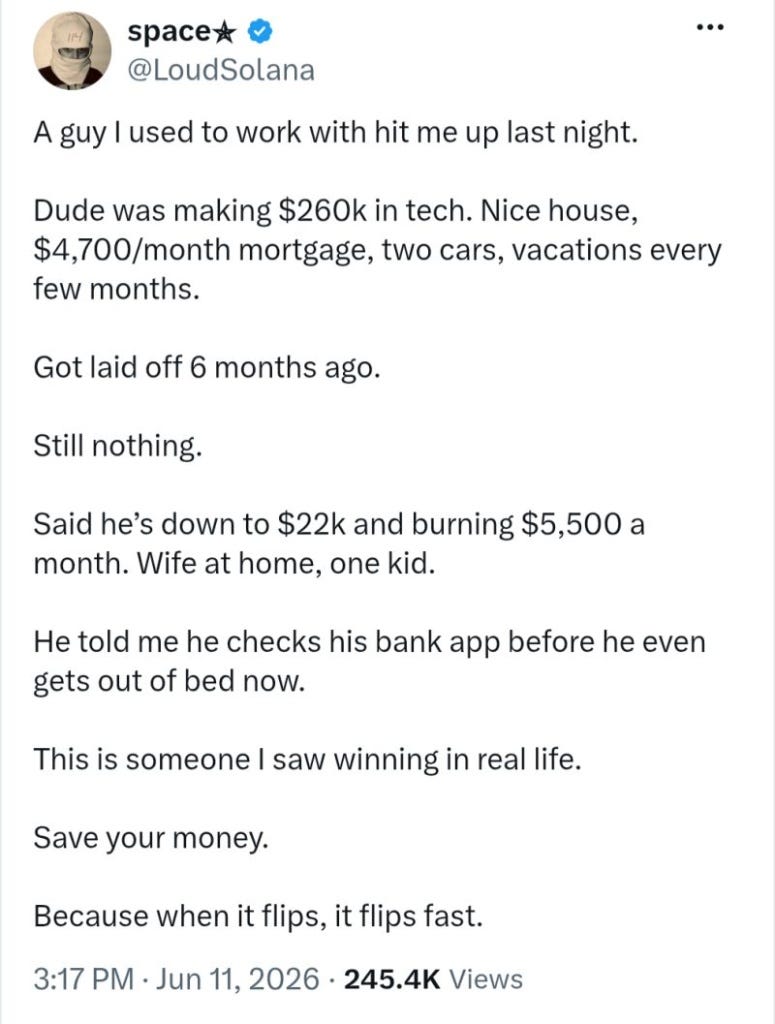
From the outside, this person had reached the summit. They were “winning in real life.” But from a systematic perspective, their financial architecture was incredibly fragile. They had built a machine that only functioned under perfect conditions. The moment the market shifted, the machine began to tear itself apart.
Here is a breakdown of why high-income earners fall into the High Burn Trap, and the mechanics of escaping it.
The Illusion of Top-Line Revenue
In business, we differentiate between top-line revenue (total sales) and bottom-line profit (what you actually keep). A company bringing in millions can still go bankrupt if its operating costs are too high.
Personal finance operates on the exact same physics. A $260,000 salary is just your top-line revenue. It is an incredible tool, but it is not wealth. Wealth is the bottom line—it is the capital you retain and deploy to buy back your own time.
The individual in the story fell victim to the most common trap for high earners: perfectly scaling their fixed costs to match their rising income.
The Gravity Well of Fixed Costs
When you optimize your life for status rather than resilience, you create a massive gravitational pull on your cash flow.
Look at the structural vulnerabilities in the portfolio:
A $4,700/month mortgage: This is a massive, inflexible anchor. You cannot easily negotiate this down or pause it when revenue stops.
Two car payments and lifestyle overhead: Pushing the baseline burn rate to $5,500 a month.
When your baseline expenses are this heavy, achieving financial “escape velocity” becomes mathematically impossible. Every dollar of that $260k income is required just to keep the engines firing and prevent a crash. When the income thrusters abruptly cut out—as they inevitably do during a cycle of layoffs—the descent is terrifyingly fast.
The Mathematics of Ruin
The most alarming part of the story is the countdown clock: $22k in the bank, burning $5,500 a month.
That is exactly four months until total ruin.
For someone accustomed to a quarter-million-dollar lifestyle, four months is barely enough time to update a resume, navigate multi-round corporate interviews, and secure an equivalent role in a tightened job market. The psychological toll of watching that $22k dwindle by $183 every single day is what leads to checking the bank app at 6:00 AM.
They held a highly leveraged position on their own career with absolutely zero hedge.
Building Systematic Resilience (Quiet Wealth)
The antidote to the High Burn Trap is decoupling your consumption from your income. It requires a shift toward anti-consumerist values, where you measure success not by what you own, but by how long you can comfortably survive without a paycheck.
To build a truly resilient system:
Define Your True Burn Rate: Do not guess. Calculate the exact fixed cost of your existence. This is the baseline number your entire safety net must be built around.
Size Your Emergency Fund to Your Lifestyle, Not Averages: The standard “three months of expenses” advice is insufficient for specialized, high-income roles that take longer to replace. If your burn rate is $5,500, a resilient safety net is $66,000 (12 months), minimum.
Optimize for Time, Not Luxury: The goal of independent research, trading, or building equity is not to buy a more expensive car. It is to purchase autonomy. Quiet wealth is driving a modest vehicle from a fully paid-off home, knowing your portfolio generates enough yield to cover your baseline.
A high income can make you feel invincible, but the math is undefeated. When the market flips, it flips fast.
Don’t build a bigger trap. Build a stronger safety net.
If you are interested in applying mathematical rigor to your personal finances and building systematic, quiet wealth, you can find more models and research at richtuga.com and by subscribing to the RichTuga newsletter.